Getting rich trading versus staying rich in the stock market
When it comes to investing, there are two distinct frames of mind a trader can approach the stock market with — a “Get Rich” mindset or a “Stay Rich” mindset.
These two approaches pursue two very different goals and therefore require fundamentally different strategies or portfolio compositions. The concepts of capital preservation versus wealth accumulation have long been staples in financial planning, but the terms “Get Rich” and “Stay Rich” were popularized (at least for me) by Meb Faber in his 2020 blog series.
Let’s dive into how to build portfolios with these goals in mind and hopefully give you some ideas to come away with for yourself.
I recorded a video overview of everything in this article, so if you prefer to sit back, relax, and watch instead of reading, hit play below. We also have timestamps in the description of the video in case you want to jump around.
The “Stay Rich” portfolio: a wealth preservation strategy
Don’t let the name “Stay Rich” mislead you—wealth is a relative concept. Whether you’ve stashed away $25,000 by age 30 or have millions in assets, the defining characteristic of a Stay Rich portfolio is its focus on protecting what you’ve already earned. If you can’t afford to lose it, it belongs in this bucket.
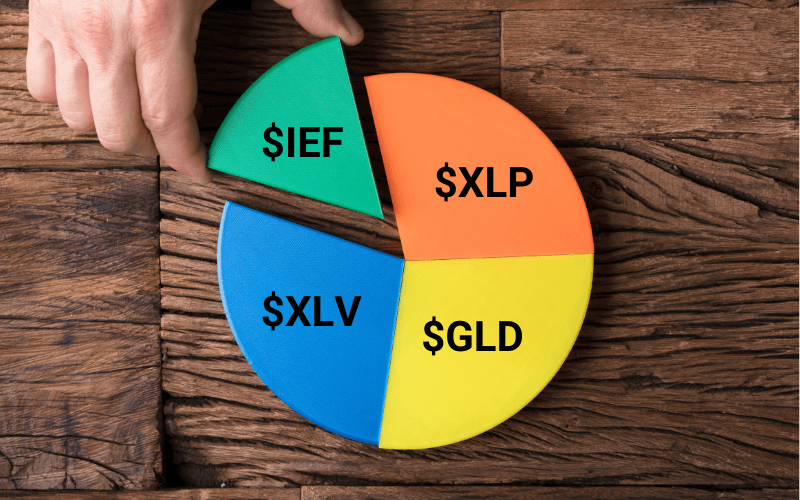
At its core, the Stay Rich portfolio is designed for wealth preservation. While stability is the priority, simply hoarding cash isn’t an effective strategy. We know that inflation steadily chips away at purchasing power over time and this means even the most conservative investors need some level of market exposure to keep pace with rising costs.
The challenge lies in striking the right balance: minimizing risk while achieving enough growth to outpace inflation and earn a real return. This is why Stay Rich portfolios emphasize diversification, low volatility, and protecting against catastrophic losses.
Key Features: Diversification, low volatility, or active risk management.
Examples: Bonds, TIPS, gold, conservative stock portfolios, or a barbell strategy.
The “Get Rich” portfolio: the path to accumulate wealth
The Get Rich portfolio is what you often see glamorized on social media. It’s all about high growth, high-risk opportunities, and shooting for the moon. Unlike the Stay Rich portfolio, the focus here isn’t on maintaining stability week to week—it’s on generating aggressive returns over a longer time horizon.
Volatility and drawdowns? Bring it on! Those are features and not a bug to reach a Get Rich investment goal.
This strategy often appeals to younger investors or those who are in a position to take outsized risks to accumulate wealth quickly. It frequently involves concentrated investments in speculative or high-growth assets, which can lead to significant emotional and financial swings.
Key Features: High volatility, potential for outsized returns, and a willingness to endure emotional ups and downs.
Examples: Individual stocks, emerging technologies, options, or leveraged investments.
Most investors should have both portfolios
While the Stay Rich and Get Rich portfolios represent two distinct philosophies, it often makes sense to establish both sets of portfolios (strategies) at the same time. I know this is extra work and slightly more confusing but you’ll thank me years down the line when your investing goals begin to shift and you already have the right foundation in place.
Let’s take, for example, a 30-year-old investor pursuing a “Get Rich” strategy. This person might have 95% of their capital in concentrated growth investments to match their investing goals, and if they maintain even a 5% weight in a “Stay Rich” strategy on the side, that will begin building the muscle memory and live trading experiences of what it looks like protecting capital which will be important down the line.
As the years go by and the risk tolerance and investing goals shift, this investor will want to consider slowly rebalancing capital out of the growth bucket and into the preservation bucket.
The mix of these portfolios should evolve over time, reflecting your age, goals, and risk tolerance. As you get older, it’s natural to shift a larger share of your investments into the wealth preservation bucket.
How Evan Medeiros invests in the stock market
For my personal investing, I use the same Stay Rich and Get Rich philosophy outlined throughout this article and invest in the following buckets:
- Evan’s Stay Rich Portfolio: I invest in my trading systems Merlin, Lamorak, and Galahad for wealth preservation. The purpose of these trading systems isn’t to triple my account size in 12 months but instead to preserve capital while still achieving growth that outpaces inflation (and hopefully the S&P500 over the long haul).
- Evan’s Get Rich Portfolio: This portion of my capital involves investing in individual stocks, Bitcoin, and other speculative assets. These are generally higher beta, higher risk, and concentrated positions designed to achieve faster capital growth. I’m not trying to risk manage every 1-month swing in these positions, instead, I’m trying to identify durable secular trends that have the potential to last multiple years or even decades and let the magic of compounding and time in the market compound for me.
I use my trading systems to risk manage my hard-earned capital and grind out profits over time and I use my concentrated investing accounts to earn outsized gains. If my investing accounts have a great year I’ll rebalance some of those profits into my trading accounts where the capital will be risk-managed and treated a little more kindly.
Conclusion
Articulating your investing goals and then building portfolios and strategies constructed to achieve those goals will align your actions and set you up for success.
As with most things in investing and finances, there’s no one-size-fits-all solution for everyone. Your own personal style, goals, risk tolerance, and more will help guide your decision into what a Stay Rich and Get Rich portfolio should look like and how much capital you should be allocating to each.
It may not seem like it right now, but you will want to change your allocations over time. Having both strategy buckets in place now will make adjusting their weightings over time easier.
Was this article helpful? How do you approach this balance? I’d love to hear your thoughts and strategies in the comments below.
Enjoy what you read? Share it below and be sure to tag @thetraderisk.
